Deindustrialisation in Europe is more bogeyman than reality
In this guest article, Nico Palesch, an industry economist at Oxford Economics, argues that reports of the death of European industry — like Mark Twain’s apocryphal demise — have been greatly and repeatedly exaggerated.
The most recent high-profile obituary was issued by Belgian Prime Minister Alexander De Croo, who in September 2022, at the high point of spiking European gas prices, used the term “deindustrialisation” to describe what he feared could happen.
He warned that unless Europe acted, the continent faced the prospect of large-scale losses of manufacturing jobs and capability. European industry has nonetheless so far shown little sign of giving up the ghost.
The broad-based and deep industrial recession that was forecast by many observers has failed to materialise. In fact, industrial production as a whole declined only moderately at the end of 2022, at a level comparable to the decline seen in the US.
Of course, European and the UK governments did in fact step in and, to a large extent, shielded consumers and businesses from higher gas and electricity prices. But it is important to understand why the narrative about a European deindustrialisation is misleading.
A look under the sectoral hood reveals that, while energy-intensive industries — in particular the chemicals sector — have been hit hard in terms of sharply falling output, this has hardly been the case across most sectors.
Most saw low growth or small contractions over the second half of 2022 as the gas crisis really began to bite. Energy-intensive sectors will be the main losers: structurally higher energy prices in Europe will still have a deleterious effect on them.
Chemicals, metals, paper, and refining have been hit hard by the energy shock and will likely experience a permanent reduction owing to reduced competitiveness. The negative outlook for this set of industries is perhaps best illustrated by the announcement by German chemicals manufacturer BASF that it will shut down ammonia and fertiliser production facilities within Europe in light of higher energy costs.
On the other hand, industry at large has proven quite resilient. Some of this can be traced back to the aforementioned government support, but firms’ actions also made a difference. The IEA has attributed industrial gas savings to fuel switching, efficiency gains, and production curtailment, with the latter being compensated by increasing imports of energy-intensive intermediate goods that have helped cordon off negative effects of high gas prices on output to directly affected sectors.
Longer-run fears about a decline in European manufacturing tend to centre around competitiveness relative to Asia and, to a certain extent, the US. Our longer-run economic forecasts do indeed predict that, over time, more and more of the world’s total manufacturing activity will be in Asia Pacific.
Specialists, not dinosaurs
One could be forgiven for looking to the past as a guide; European factories did close, and thousands are jobs have been “lost” to cut-price Asian manufacturers in the past decades, particularly in the 1980s and 1990s as the share of GDP made up by manufacturing shrank, but the industrial operations that have survived that revolution are very different from the dinosaurs of the 1970s and 1980s.
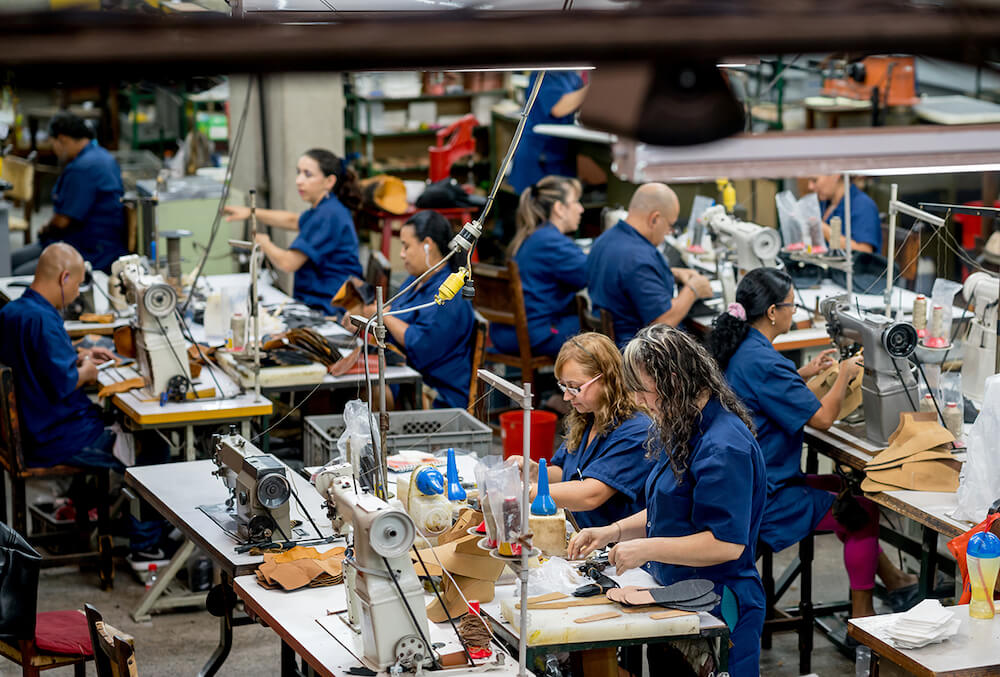
Sectors such as textiles, leather, and clothing, which has long seen a migration of production to Asia, will likely continue to lose out to a high share of low-skill labour costs that will allow firms in the Asia Pacific region to cannibalise some level of European production.
But many sectors, given the high value-added specialisation in much of Europe’s manufacturing, will continue to benefit from the region’s highly educated workforce, research institutions, infrastructure, and existing firms’ technological know-how and advantages.
We expect growth in European sectors such as basic metals, non-metallic minerals, and motor vehicles and parts will match Asia, a sign of Europe’s strong comparative advantage in these areas.
In the long run, we expect European industry to grow alongside GDP and thus to roughly maintain its share of total output. Higher growth in the Asia Pacific region will mean that more of the world’s manufacturing will be in that region, but we are forecasting that this will for the most part not come at the expense of Europe.
Warnings of imminent catastrophe have proven effective at spurring European policymakers to act — first by decisively stemming the gas crisis, and second by matching the subsidies in the US Inflation Reduction Act which have also been labelled an existential threat to the continent’s industrial future.
But industry is not so easily killed – individual sectors may shrink, some production may migrate, but rather than preparing a requiem, government and business would be better advised to focus on, defend, and expand Europe’s many vibrant sectors and strengths.
#modernglobalnews #modernglobalbusiness #modernbusinesseurope #health #france #russia #germany #unitedkingdom #italy #ukraine #switzerland #netherlands #greece #poland #spain #news #business #europe #market #stock